
Personal Insurance
Home, condo, tenant, auto, recreational and high-value coverage for households across Atlantic Canada — placed by brokers who read the wording before they quote the price.
01 / Our Approach
The Policy You Have Is Not Always the Policy You Think You Have
Most households find out what a policy actually says after the water damage, the collision or the break-in. The limits, the deductibles, the replacement-cost wording and the exclusions sitting behind them vary far more between insurers than the premium does — and the differences only show up at claim time.
Water is the clearest example. In Canada, overland water and sewer backup are optional endorsements, not part of a standard home policy, and storm surge is excluded even where an endorsement is available. On a coastal property that distinction decides the claim. Stanhope Simpson places home, condo, tenant, auto, recreational and high-value coverage for clients across Nova Scotia, New Brunswick, Prince Edward Island and Newfoundland and Labrador, including the group-rated programmes we run for association members.
Coverage for the Whole Household
Ten policies, each with its own page. Most households need three or four of them, reviewed together rather than renewed separately.

The building, the contents, the liability and the water endorsements that are not in the standard form.
Improvements and betterments, contents, liability, and your share of the corporation’s deductible.

Contents, personal liability and somewhere to live while the unit is repaired.
Liability well above the statutory minimum, Section B, direct compensation and physical damage.

The liability policy the Off-highway Vehicles Act requires the moment you leave your own land.
Hull, liability, agreed value and the lay-up terms that decide winter coverage.

Registered, trail-legal coverage for sleds, with the same off-highway rules as an ATV.
Guaranteed replacement cost, scheduled valuables and liability limits that match the balance sheet.

Agreed value on the items that sit under a special limit in a standard policy.
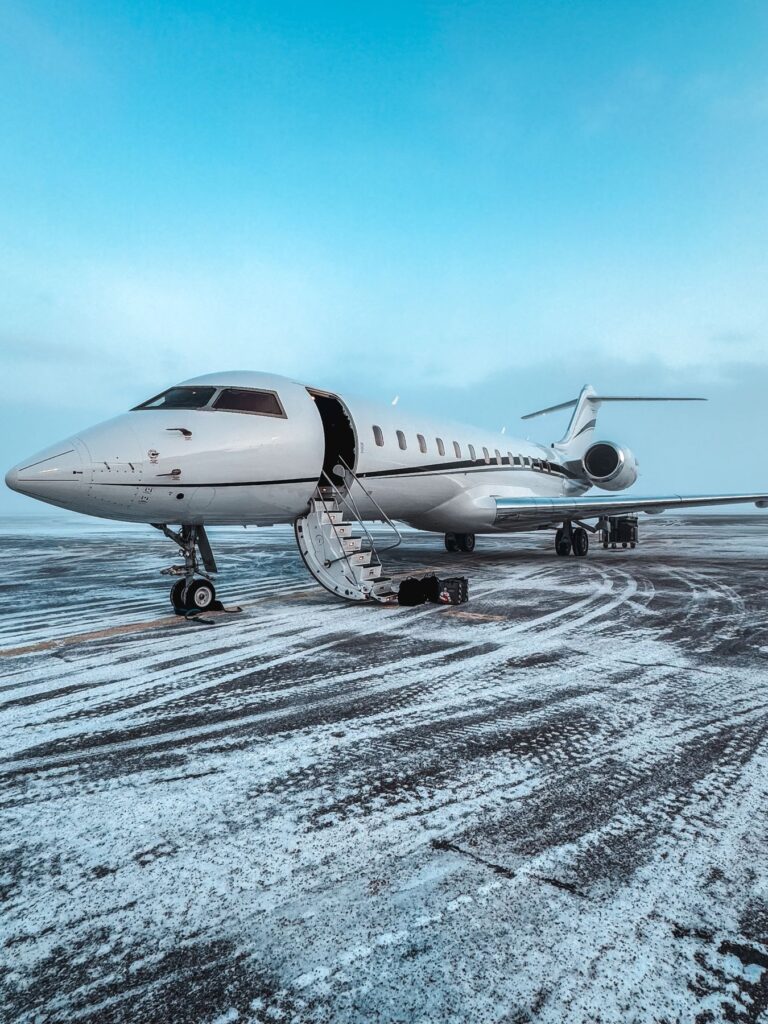
Hull and liability for private aircraft, and the pilot warranty behind the coverage.
03 / At a Glance
What You Own, What Goes Wrong, and What We Place
The short version of why each of these has its own page. Each row names the thing that actually decides the claim.
Wordings, sub-limits and available endorsements vary by insurer and by risk. This describes what these programs are built to address, not what any particular policy will pay — your own wording governs.
What you own |
What actually goes wrong |
What we place |
|---|---|---|
Insured loss figures: Insurance Bureau of Canada, January 2023 (Hurricane Fiona) and July 2024 (2023 Nova Scotia wildfires and flooding). Catastrophe totals are restated over time.
04 / The Gaps
Where Personal Policies Most Often Fall Short
Hurricane Fiona caused more than $800 million in insured damage, the costliest extreme weather event ever recorded in Atlantic Canada, and the 2023 Nova Scotia wildfires and flooding added roughly $490 million more.* The gaps below are the ones that turn up afterwards, and every one of them is visible on the declaration page beforehand.
- Water the standard form never covered. Overland water and sewer backup are optional endorsements in Canada, not part of a standard policy — and storm surge is excluded even where the endorsement is available, which is the distinction that matters on a coastal property.
- A rebuild limit set at an older price level. Replacement cost pays today’s cost of materials and labour. Guaranteed replacement cost goes beyond the stated limit, but only where the insurer’s conditions have been met, and those conditions differ between carriers.
- Special limits nobody mentioned. Jewellery, cash, bicycles, coins, collections and business property kept at home each sit under a sub-limit, and those sub-limits vary widely — jewellery alone runs from about $1,000 to $6,000 depending on the form.
- A condominium deductible charged back to the unit. Corporation deductibles for water damage now reach six figures, while a standard unit owner’s policy may reimburse only a fraction of one. The gap lands on the owner.
- A liability limit left at the statutory minimum. Nova Scotia requires $500,000, the highest minimum in Atlantic Canada and still well below what a serious injury award can reach. The difference comes out of the household.
- A recreational vehicle assumed to be covered by the home policy. Watercraft extensions carry horsepower and value ceilings, and an ATV or snowmobile needs its own liability policy the moment it leaves land you own or occupy.
- Two policies that were never reviewed together. Home beside auto, boat beside home, valuables beside contents — losses fall into the space between them.
05 / Our Method
How We Review a Household Program
The same method behind all ten pages, and behind the programs we place.
- Start with the declaration pages. What you own, how it is held, and what each policy already says — before anyone quotes a price.
- Price the rebuild, not the purchase. A dwelling limit set against an older construction cost is the most common reason a claim settles short.
- Find the sub-limits. Jewellery, art, collections, bicycles and business property at home either fit under the limit or get scheduled at an agreed value.
- Put the household on one review cycle. Home, auto, boat and valuables move at different speeds. Reviewing them together is how the gaps between them get found.
- Go to the markets that fit the household. We hold access to more than fifty insurer and surety markets, standard and high-value alike, and we know which of them write each of these classes properly.
- Review it every year, with the same broker. Values move, households change, and the program has to move with them.
06 / Group Programs
Home and Auto Through Your Association
A group programme applies a negotiated rate to the same coverage you would buy on your own — the same forms, the same limits, the same deductibles — priced for the group rather than the individual. Eligibility runs through membership rather than employment: premiums are paid entirely by the person insured, and there is no payroll deduction or employer cost to administer. Because the rate is applied through whichever insurer actually fits the household, the programme has to run through a broker rather than a single carrier.
- CANS Home & Auto Program — for employees of Construction Association of Nova Scotia member companies.
- CAPEI Home & Auto Program — for employees of Construction Association of Prince Edward Island member companies.
- The same coverage, not a stripped-down product. You keep the forms, limits and endorsements you would have chosen on your own.
- Placed with whichever insurer fits the household. The group rate follows you to the right market rather than tying you to one carrier.
- It reaches further than you think. A spouse or common-law partner is included, and so are children under 25 living at home or away at school full-time.
- How the programmes work — eligibility, what it costs a member company, and how to join.
07 / Alongside
What Sits Alongside a Personal Program
- Business insurance — the commercial program for the company, reviewed beside the household that owns it.
- Insurance by industry — sector programs for the seven industries we write most deeply.
- Construction & Development — for builders and developers, including the personal exposures that come with them.
- Surety bonds — bid, performance and commercial bonds, handled by the same office.
08 / Questions
Frequently Asked Questions About Personal Insurance
Only some of it. Damage from a burst pipe inside the home is normally covered. Water that arrives from outside is not: overland water and sewer backup are optional endorsements that most Canadian insurers now offer, but they are not part of a standard policy and have to be added. Storm surge and tidal water are excluded even where the endorsement is available, which is the point that matters most on a coastal Nova Scotia property. Availability is also risk-rated, so a home in a mapped flood area may find the endorsement expensive or unavailable. We check what your current policy actually carries before recommending anything.
The corporation insures the building and the common property, and in Nova Scotia the boundary is set by the standard unit description registered for your development — that document decides which components the corporation insures and which are yours. Your own policy has to cover contents, any improvements and betterments above that standard unit, personal liability, loss assessment, and your share of the corporation’s deductible. That last one has become the important one: corporation water deductibles now reach six figures, while a standard unit owner’s policy may only reimburse a small fraction of one. Higher deductible assessment limits are available, and we will tell you what yours is set at.
Nova Scotia’s statutory minimum is $500,000 — the highest in Atlantic Canada, where New Brunswick, Prince Edward Island and Newfoundland and Labrador all sit at $200,000. It is still a low ceiling against a serious injury award. Most brokers in this market write $1 million or $2 million, because the cost of the increase is small relative to what sits behind it, and because anything above your limit comes out of your own assets. The matching piece is Family Protection, which steps in when the driver who hits you carries less than you do.
For an ATV or snowmobile in Nova Scotia, yes, and it is a legal requirement rather than a recommendation. The Off-highway Vehicles Act requires a motor vehicle liability policy of at least $500,000, plus accident benefits and uninsured coverage, for anyone operating on land they do not own or occupy, and the machine has to be registered. Riding only on your own property is the exception. Boats are different: no law requires insurance, but a home policy’s watercraft extension carries horsepower and value ceilings that most real boats exceed, and marinas and lenders generally require proof of cover. Above those ceilings you want a standalone marine policy, with agreed value and lay-up terms you have actually read.
Schedule it. Every standard Canadian homeowner form caps jewellery, watches and furs at a sub-limit — depending on the wording, somewhere between roughly $1,000 and $6,000 in total, not per item. Cash, bicycles, coins, stamps, collections and business property kept at home all carry their own separate caps. Scheduling puts a named item on the policy at an agreed value, usually with no deductible, so a total loss pays the agreed figure rather than the sub-limit. Insurers ask for an appraisal above certain values; below those, a detailed description and a value are normally enough. Keep the values current — metal and stone prices move.
You deal with us. The broker who placed the policy is the one who reads the wording back against what happened, deals with the adjuster and tells you honestly where the policy stands. That is the practical reason to keep the household’s policies in one office rather than spread across three portals — when a loss falls between two policies, somebody has to be looking at both of them.
Talk to a Personal Lines Broker
Send us your current declaration pages and we will tell you what the policies actually cover before we quote them. You will hear back from a broker who handles the file themselves — not a call centre.
Ready to Review Your Household Coverage?
One conversation and your current declaration pages are enough to tell whether the coverage fits the household. If it does, we will say so.
Call (902) 454-8641, email info@stanhopesimpson.com, or use the form — whichever is fastest for you.